

01
A person gets hurt.
A collision with a pedestrian can involve medical bills and a claim against the rider or another responsible person.
THE QUESTION TO ASK
Who is protected if our family faces a liability claim?
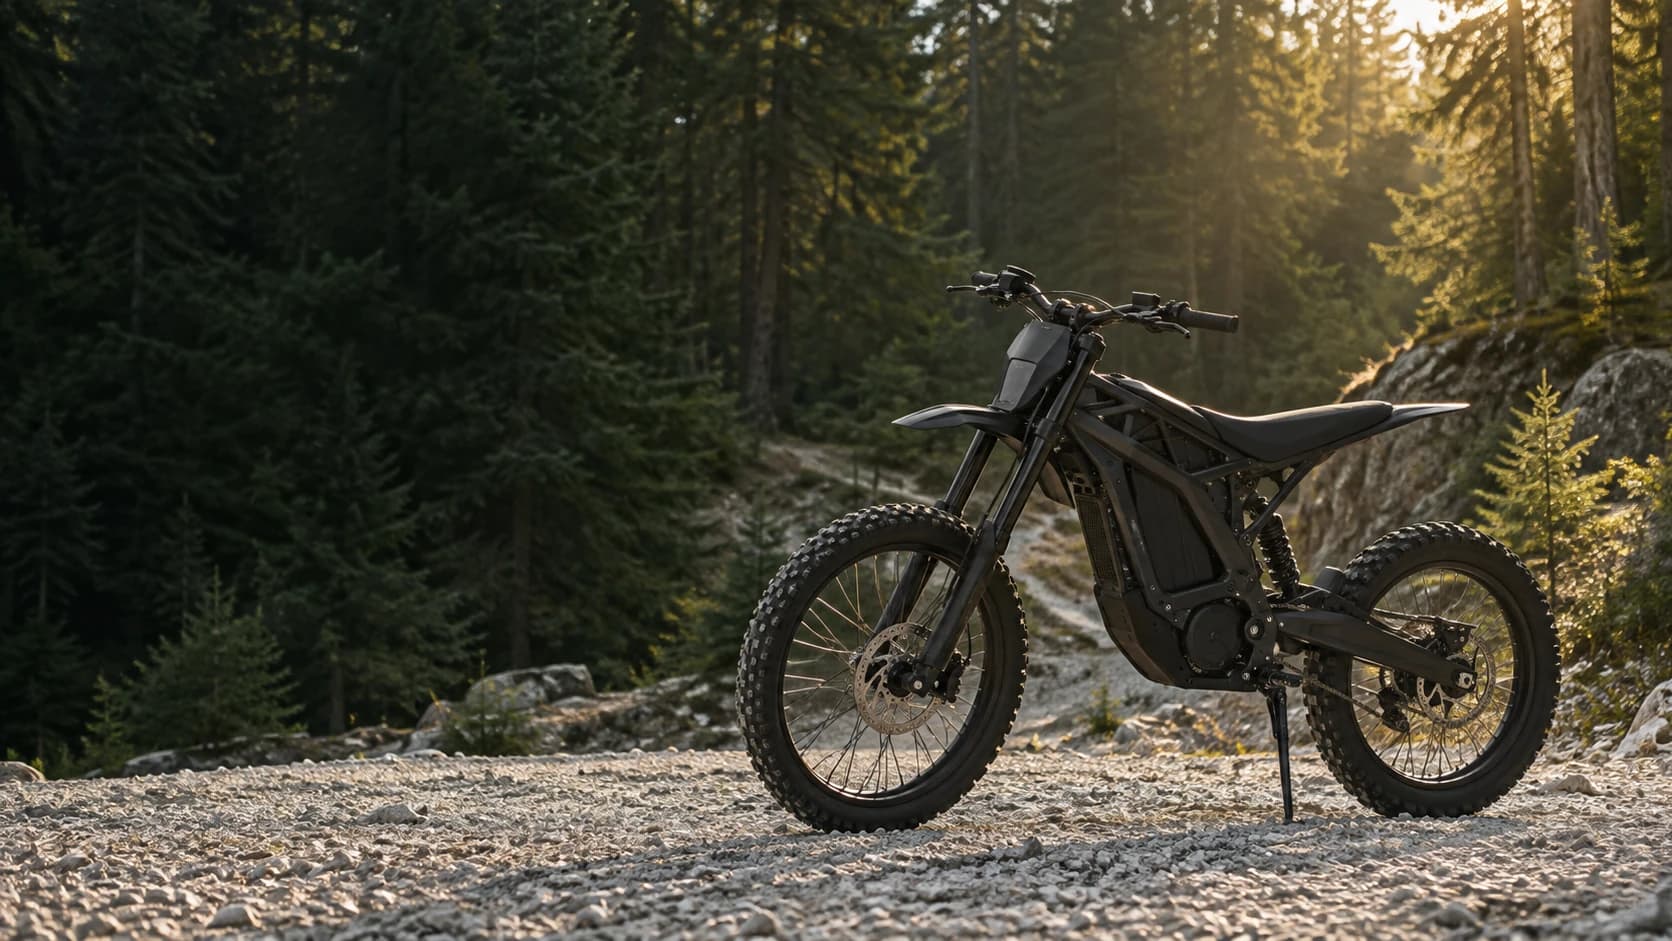
SURRON & ELECTRIC DIRT BIKE INSURANCE
For riders who love the freedom. And parents who know there’s more at stake than a bike.
Build my coverage checklistNo contact details needed · No obligation
01 / THE BIGGER PICTURE
A parent’s guide to what mattersThe rider may be your child.
The financial responsibility may reach you.
If a young rider injures someone or damages property, parents may face a claim too. Responsibility depends on state law, ownership, permission, and the circumstances.
A thoughtful insurance review starts with your family’s exposure, alongside the cost of replacing the bike.
Understand the parent liability questionA collision with a pedestrian can involve medical bills and a claim against the rider or another responsible person.
Who is protected if our family faces a liability claim?
A ride ends with damage to a parked car, a fence, or someone else’s belongings. Repair costs may become your concern.
Does liability coverage follow this rider and this use?
Theft raises a different coverage question from liability. The bike’s value, deductible, and storage conditions matter.
What would a covered theft actually pay to replace?
Illustrative situations, not actual claims or coverage guarantees. A policy’s terms determine whether a loss is covered.
IN THE NEWS
Sources reviewed September 15, 2026Independent reporting and public safety guidance bring the stakes into focus. Read the source, understand the context, and know what to ask for your family.
Select to load ABC7’s player. ABC7 may use cookies.
ABC7 reported that Orange County prosecutors created a dedicated unit to review illegal riding, including cases involving parents alleged to knowingly allow it. The report describes charges against three parents.
Watch or read at ABC7Is this rider allowed to use this bike, in the places they actually ride?
Police reported that a pedestrian suffered serious injuries in a collision involving an electric dirt bike described as a 2025 Surron. The report does not establish a minor rider or parent involvement.
Read the police reportReview protection for injuries to other people.
California’s attorney general urged families to check power, speed, and operable pedals. A vehicle sold as an e-bike may have motorcycle or moped requirements.
Read the consumer alertConfirm the bike’s classification before choosing a policy.
The video describes charges at publication, not convictions. Criminal responsibility and civil liability are different. These reports do not establish insurance coverage for an incident or criminal penalties.
Turn the headlines into a checklist for your family.
AN IMPORTANT DISTINCTION
A battery is a power source. It is not an insurance classification. A Surron electric dirt bike needs a review of its actual design, specifications, and use.
See the manufacturer and policy guidanceMany e-bike policies are designed for pedal-equipped bicycles within defined power and speed limits.
Explore motorcycle or off-road markets. Confirm the exact bike, rider age, modifications, and riding location.
MODEL-SPECIFIC REVIEW REQUIRED02 / PROTECTION, EXPLAINED
The right questions make the differenceSix conversations to have before choosing a policy. Availability and terms depend on the insurer, bike, rider, and state.
A covered accident could mean someone else’s medical bills, damaged property, and a legal claim.
Are both the rider and the parent or owner protected?
Explore comprehensive coverage for theft and certain losses beyond a collision.
What value, deductible, and storage conditions apply?
Ask about protection for damage to the bike in a covered crash, regardless of fault.
Are the battery and declared accessories included?
Your rider’s medical needs deserve their own conversation alongside health insurance.
What medical or uninsured motorist options are available?
An umbrella may add another layer of protection for covered claims above underlying limits.
Does it accept this bike, every rider, and the intended use?
Off-road recreation, street use, modifications, and competition need different consideration.
Does the policy match what actually happens on a ride?
Coverage should fit the real ride. A quote or policy for an adult or a different bike is not confirmation that your child’s Surron use is insured.
THE “WE ALREADY HAVE INSURANCE” QUESTION
Your home, health, and umbrella policies each do a different job. The useful question is how they respond to this particular bike and rider.
Check the questions that matterMotor-vehicle liability can be excluded. Theft coverage and liability coverage must be checked separately.
Read about common exclusionsAn umbrella has its own rules. Verify the bike, every rider, underlying limits, and excluded activities.
Understand umbrella requirementsLiability generally addresses injuries and damage to others. The rider’s own medical protection needs a separate review.
Explore motorcycle coverage types03 / A CLEAR PATH FORWARD
Less guessing. A better conversation.Start where you are, whether the bike is already in the garage or still on a wish list.
Choose your state, bike, youngest rider, intended use, and modification status. No contact details required.
See the coverage and eligibility questions that matter for your answers. Keep it, copy it, or share it.
Add your contact details to send your checklist and bike answers to our quote team. An agent must confirm eligibility and available markets.
START WITH YOUR FAMILY
You don’t need to know insurance.
You just need to know your rider.
Florida inquiries: Truscott Insurance Solutions.
California inquiries: Kousa Insurance & Financial Services.
View licensing & disclosures
THE RULES ARE LOCAL
Riding access, licensing, and parental responsibility depend on where you live and ride. These are examples to discuss, not a determination of your legal liability.
Florida law can make the signer of a minor’s driver-license or permit application liable for damages from that minor’s driving of a motor vehicle on a highway, subject to statutory provisions. That is a specific rule, not blanket liability for all parents and all trail riding.
The state’s electric-bicycle definition includes working pedals and motor and class limits. Verify the actual bike’s classification and riding permissions.
Florida § 322.09Florida vehicle definitionsA negligent-entrustment claim can arise when someone permits an unfit driver to use a vehicle, knows or should know of the unfitness, and that unfitness contributes to harm. The facts matter; parental status alone does not establish this claim.
California DMV’s 2026 guidance classifies qualifying pedal-free, manufacturer-designed off-highway electric motorcycles as off-highway motorcycles subject to OHV identification requirements. Registration does not itself permit street or bicycle-path use.
Judicial Council: CACI 724DMV 2026 eMoto guidance04 / GOOD QUESTIONS
For the parents doing their homework.
And the riders who want to get it right.
A Surron may need a motorcycle or off-road vehicle policy rather than a standard electric-bicycle policy. Availability must be confirmed for the exact model, year, VIN or serial number, state, rider, modifications, and use. A carrier advertising motorcycle insurance does not establish that it will accept your Surron. This page helps you prepare that conversation; it does not confirm a carrier placement.
Yes, parents or other responsible adults may face a claim, depending on the circumstances and state law. Possible grounds include allowing an unfit rider to use a vehicle, ownership-based responsibility, or a specific statute. Being a parent alone does not automatically make you liable for every accident. Review coverage for the actual rider and the parent or owner, and ask a lawyer about your legal responsibilities.
Do not assume it does. Homeowners policies commonly contain motor-vehicle exclusions, and coverage for liability is a separate question from coverage for damage to or theft of the bike. Exceptions and definitions vary. Ask your insurer to review the exact model, where it is used, and the relevant policy language in writing.
That depends on the insurer’s age rules, the motorcycle, the state, and the intended riding use. The youngest rider should be disclosed from the start, along with every other intended rider. Eligibility for an insurance policy and legal permission to operate the bike are separate questions. Disclose that your child will ride and ask the insurer to confirm that child’s eligibility and coverage in writing.
No. Insurance does not change the bike’s classification or replace registration, licensing, equipment, age, or riding-access requirements. For example, the manufacturer’s 2025 Light Bee X manual identifies the X as an off-road version and prohibits public-road riding. Verify the exact version and local rules; adding pedals or choosing a lower power mode does not establish legal bicycle status.
Liability generally addresses covered injuries or property damage to other people. The rider’s own injuries need a separate review of health insurance and any available medical payments, uninsured/underinsured motorist, or other applicable coverage. Those options and their exclusions differ by state and policy.
Comprehensive coverage may address theft and certain non-collision losses; collision may address crash damage. Ask about settlement value, deductibles, battery coverage, storage conditions, accessories, and exclusions. Disclose motor, controller, battery, speed, and other changes before coverage is issued. Modifications can change eligibility and what an insurer agrees to cover.
An umbrella may add liability protection for covered claims, subject to its own terms. Ask whether it accepts the specific motorcycle, off-road use, and every rider, including minors. Confirm the required underlying liability limits and any exclusions. Owning an umbrella is not confirmation that a Surron-related claim is covered.
There is no reliable one-price-fits-all figure. A quote depends on the accepted bike and rider, state, use, claims history, limits, deductibles, and selected coverage. We do not publish a starting price without a verified program and applicable rate. Begin with the coverage checklist, then ask a licensed professional to confirm availability and an actual quote.
Have the model and year, VIN or serial number, purchase price, ownership details, storage address, all riders’ ages, intended riding locations, training or licensing details, and a list of modifications. If available, bring your homeowners, health, and umbrella policy information. You can build an initial checklist here without entering your name or contact details.
THE BEST RIDES START WITH A LITTLE FORETHOUGHT.
Build your checklist first. Add contact details when you request an agent review.
These references explain vehicle classification, common coverage concepts, and selected legal rules. They do not confirm a carrier relationship or eligibility for your bike.
Additional sources are linked beside the homeowners, umbrella, rider injury, and state-law explanations above. General education only; policy terms control coverage and state law controls legal responsibilities.